





The short answer on used car loans in the UAE
Most UAE banks will finance a used car at flat rates between 2% and 4% a year, depending on the car's age, your salary, and which bank you walk into. Cars under five years old with under 100,000 km get the smoothest approvals. If you're buying something like a three-year-old Camry or Altima, you're in the sweet spot — the car holds enough value for banks to say yes without fuss.
The short version
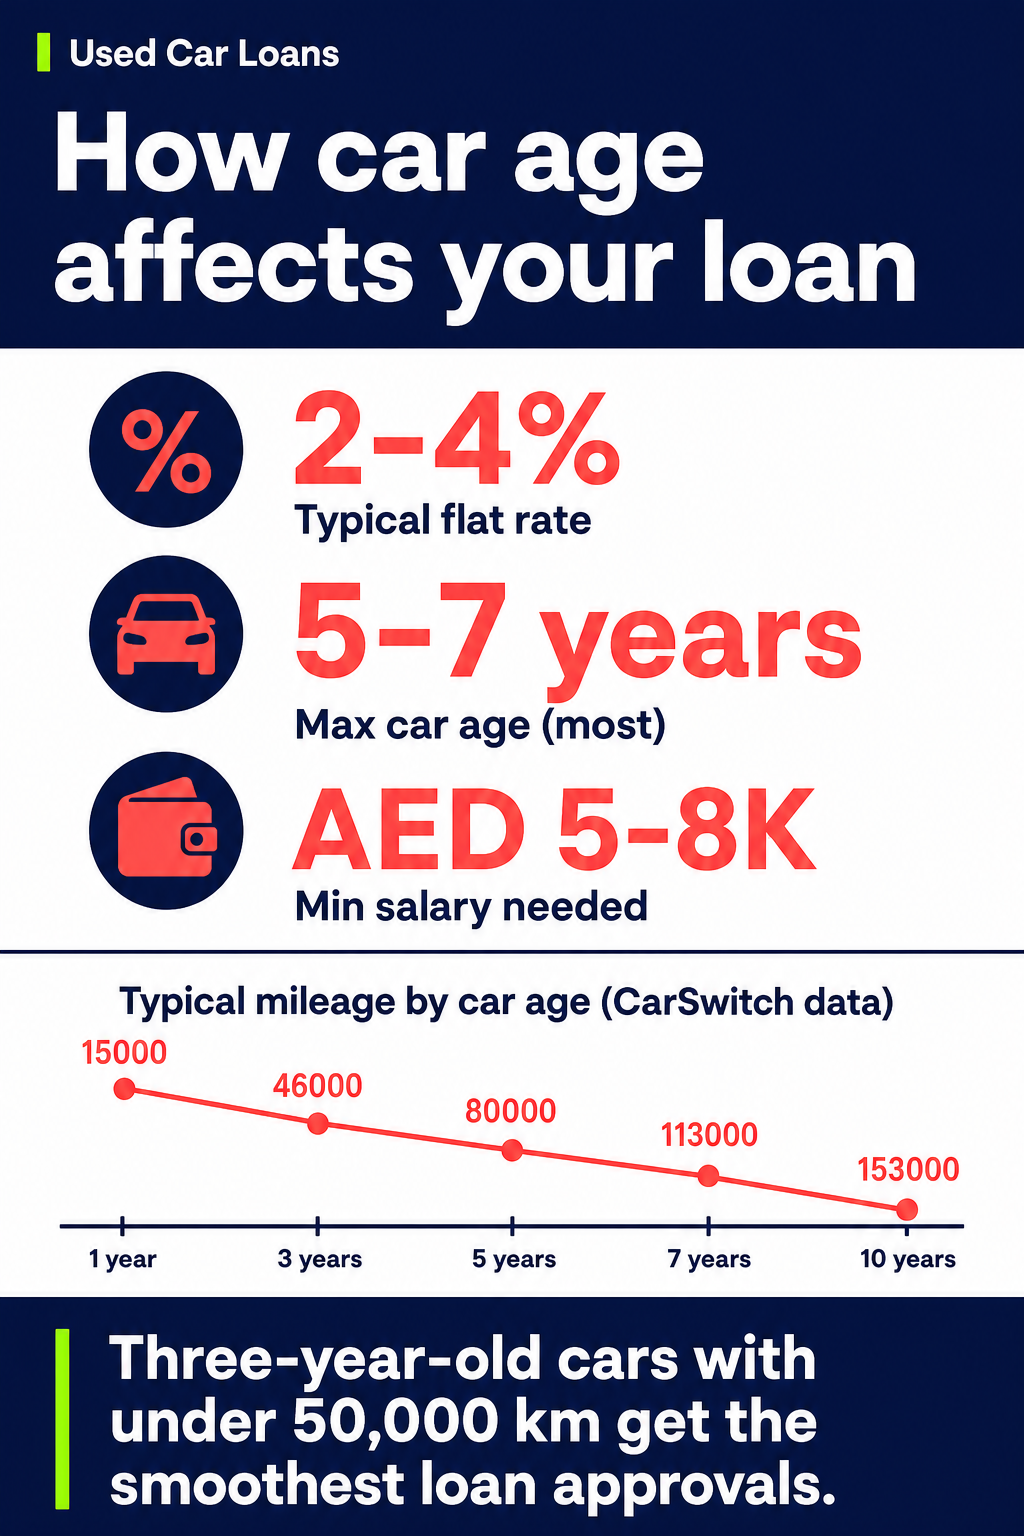
- Flat rates on used car loans typically run 2–4% per year; the newer the car, the lower the rate.
- Most banks cap financing at cars 5–7 years old; a few stretch to 10 years.
- You'll need a minimum salary of AED 5,000–8,000, depending on the lender.
- Cars under about 80,000 km get approved faster and at better terms.
- Three-year-old cars — around 46,000 km on the clock — are the financing sweet spot.
What used car loan rates actually look like right now
UAE banks price used car loans on a flat-rate basis, not a reducing-balance rate. That means if a bank quotes you 2.5% flat on a five-year loan, you pay 2.5% of the full loan amount every single year — the interest doesn't shrink as you pay down the principal.
Here's what that looks like across common loan amounts:
| Loan amount (AED) | Flat rate | Tenure | Monthly payment (AED) | Total interest paid (AED) |
|---|---|---|---|---|
| 50,000 | 2% | 5 years | 1,000 | 5,000 |
| 50,000 | 3% | 5 years | 1,083 | 7,500 |
| 80,000 | 2% | 5 years | 1,600 | 8,000 |
| 80,000 | 3% | 5 years | 1,733 | 12,000 |
| 120,000 | 3% | 4 years | 3,250 | 14,400 |
| 120,000 | 4% | 4 years | 3,500 | 19,200 |
The difference between a 2% and a 3% flat rate on an AED 80,000 loan adds up to roughly AED 4,000 over five years. That's worth shopping around for.
How car age and mileage affect your used car loan
Banks don't just look at you — they look at the car. A lender is essentially deciding whether the car will still be worth something if you stop paying. Newer cars with reasonable mileage make that decision straightforward.
According to CarSwitch listings data (July 2026), a typical three-year-old car on our platform shows about 46,000 km on the odometer. That's well within what banks consider normal. A five-year-old car sits around 80,000 km. Both are comfortable territory for loan approval.
"Banks want to see that a car's value covers the loan if things go wrong. A three-year-old sedan with normal mileage is about the easiest approval there is."
Imad Hammad, CEO and co-founder of CarSwitch
Once a car crosses seven years old — typically around 113,000 km — most mainstream banks start saying no, or they shorten the loan tenure to two or three years, which pushes up monthly payments.
The age-and-mileage rule of thumb
Here's what we see banks generally work with:
- 1–3 years old, under 50,000 km: Best rates, longest tenure (up to 5 years). Smoothest approvals.
- 4–5 years old, under 100,000 km: Still solid. Rates go up slightly, tenure may cap at 4 years.
- 6–7 years old, under 130,000 km: Fewer banks will lend. Shorter tenure, higher rates.
- 8+ years old: Most banks won't finance it. You may need to explore personal loans instead.
One detail worth knowing: a car with unusually high mileage for its age — say 100,000 km on a two-year-old car — can get flagged even if the car year technically qualifies. Banks use both numbers together.
Eligibility: what the bank looks at on your side
The car is half the equation. The other half is you. Most UAE banks ask for:
- Minimum salary: AED 5,000–8,000 per month, depending on the bank. Salaried employees with salary transfer get smoother treatment.
- Employment length: At least 6 months with your current employer (some banks ask for a year).
- Down payment: Typically 20% of the car's value. Some banks ask for more on older cars.
- Debt burden ratio: Your total monthly debt repayments — including the new car loan — can't exceed about 50% of your salary.
- UAE residency: Valid visa and Emirates ID.
Self-employed buyers can get approved too, but you'll need trade licence documents and 6–12 months of bank statements. The process takes longer.
Models that banks approve without a fight
Certain cars are easier to finance because they hold their value well and have strong resale demand. From what we see on CarSwitch, sedans and SUVs with four-cylinder engines dominate the used market — they make up about a third of all listings. Banks know these cars will sell if they ever need to repossess, so they lend against them confidently.
Three models that consistently qualify well:
- Toyota Camry: The single most popular sedan in the UAE used market. Strong resale value, and banks know it. A 2022 or 2023 Camry with normal mileage is about as safe as used car financing gets.
- Nissan Altima: Similar story — reliable, predictable value, easy to insure. The four-cylinder versions sit in that comfortable AED 50,000–80,000 range that banks like.
- Nissan Kicks: Popular with first-time buyers. Lower price point means smaller loan amounts, which means smaller risk for the bank. If your salary is on the lower end of the eligibility range, a Kicks-sized loan is more likely to get approved.
You can browse these and other inspection-verified models on our used cars in Dubai page, or check car installment options directly on CarSwitch.
A typical 3-year-old used car on CarSwitch shows about 46,000 km. A 5-year-old shows about 80,000 km. Cars with minor accident history list for about 9% less than clean-history cars — and banks notice that gap too.
Accident history matters more than you think
Banks sometimes ask for a vehicle history check, and what they find can affect the loan. Cars with minor accident history on CarSwitch list for roughly 9% less than identical cars with a clean record. That price gap tells the bank the car's resale value is weaker, which may mean a higher rate or a bigger down payment requirement.
This is one more reason to look for inspection-verified cars. When you finance through CarSwitch, the inspection report is already done — the bank can see it, and so can you. No hidden surprises. You can also explore listings in Abu Dhabi if you want a wider selection.
Timing your purchase can save you money
Here's something most people don't think about: the price of the car affects how much you borrow, and car prices shift through the year. From our data, prices in December run about 4% below the annual norm. On an AED 80,000 car, that's roughly AED 3,200 less — which means a smaller loan, less interest, and a lower monthly payment.
If you have the flexibility, shopping in the last quarter of the year can trim your total financing cost without negotiating a single dirham harder.
How to get started
Here's what happens next. Pick a car that fits your budget and falls within the age-and-mileage window banks like. Get pre-approved by your bank so you know your rate before you commit. Then browse inspection-verified cars on CarSwitch — real people are here to walk you through the financing side, and every car comes with a transparent inspection report.
You're not alone in this. Whether it's your first used car loan or your third, we handle the details so the process stays hassle-free.
 @gocarswitch
 TikTok @carswitchuae