

The answer up front
If you have the cash and you’re buying a used car in the AED 30,000–100,000 range in Dubai, paying outright will usually save you more than financing — because cash buyers can negotiate harder, and the discount they land often outweighs what that money would earn sitting in a savings account. But if pulling the full amount would drain your emergency fund, a used car loan at today’s UAE rates is still a reasonable move. Here’s how the numbers break down.
The short version
- Cash buyers we’ve seen tend to negotiate about 7% off asking — on a car listed at AED 80,000, that’s roughly AED 5,600 in your pocket.
- A five-year used car loan at around 4% flat rate adds about 20% to the sticker price in total interest.
- For cars listed under AED 30,000, the negotiation room is even wider — closer to 9% off asking.
- If you finance, put down at least 20% to keep monthly payments and total interest manageable.
- Whichever route you pick, start with an inspection-verified used car in Dubai so the price you’re negotiating from is fair to begin with.
What a used car loan actually costs in the UAE
Most UAE banks offer a used car loan at a flat rate between 3% and 5% per year, depending on the car’s age and your salary transfer arrangement. “Flat rate” means interest is charged on the full original amount for the entire term — not on the shrinking balance. So a 4% flat rate over five years is really closer to about 7–8% if you think of it the way a reducing-rate mortgage works.
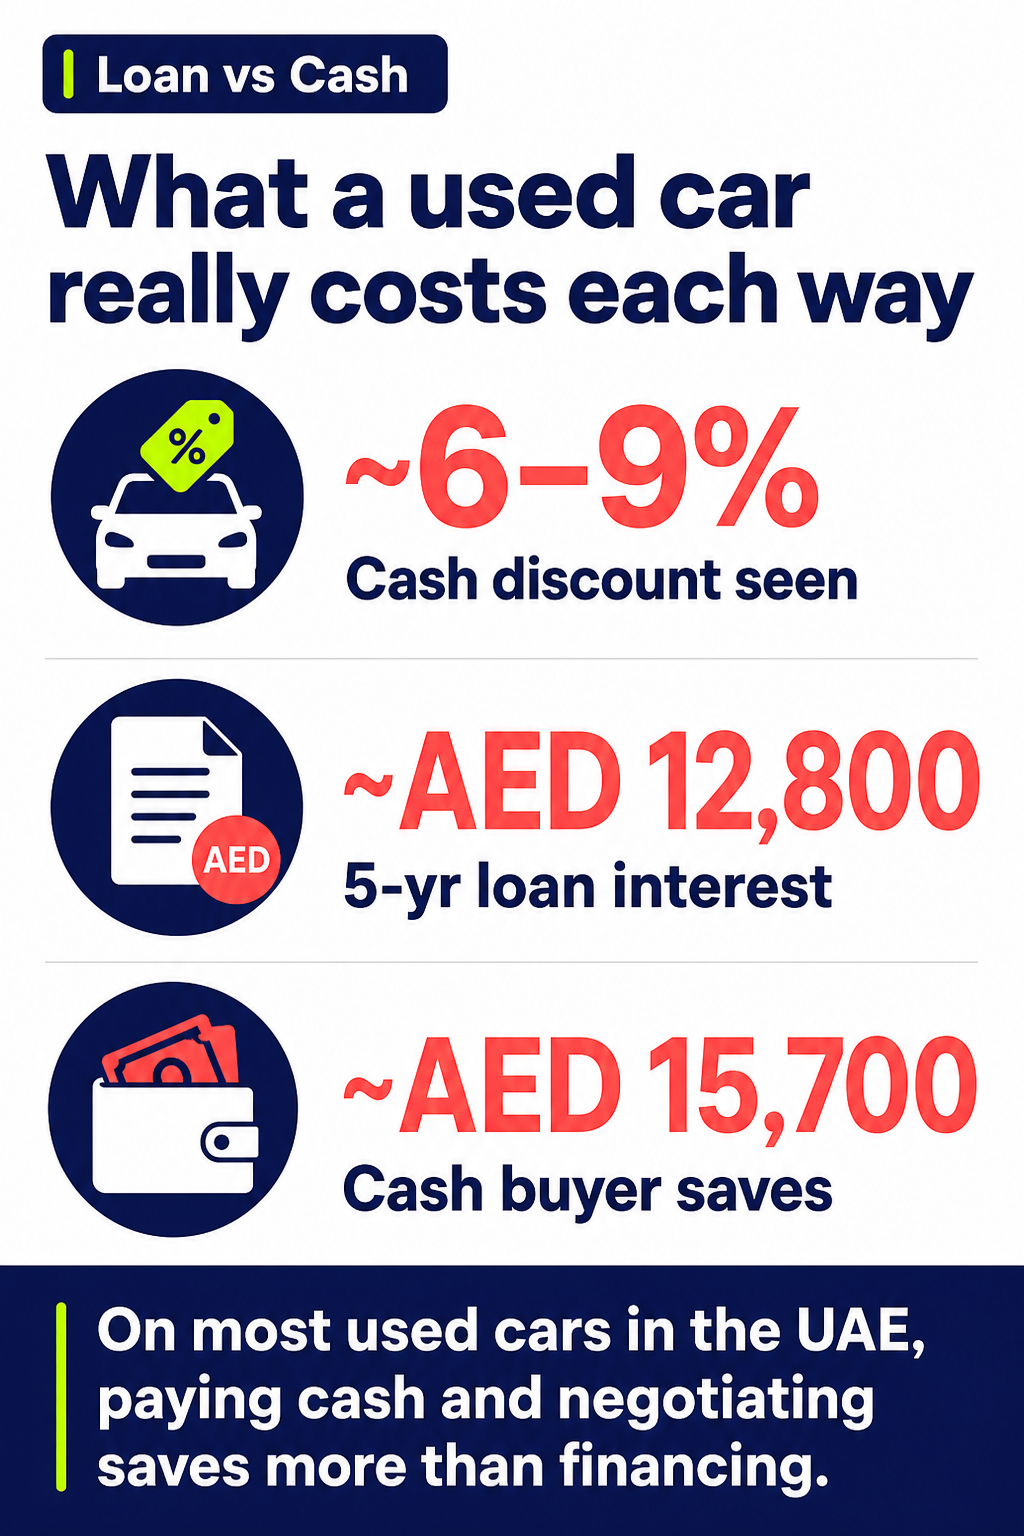
On a car priced at AED 80,000 with 20% down (AED 16,000), you’d finance AED 64,000. At 4% flat over five years, total interest comes to about AED 12,800. You’d pay roughly AED 77,000 all in — the car plus interest — before insurance and registration.
Banks also charge a processing fee (usually AED 500–1,000) and require comprehensive insurance for the loan’s full term. That’s another cost cash buyers can sometimes skip after the first year by switching to third-party cover.
What cash buyers save by negotiating
Cash talks. Sellers know a cash buyer means a faster, smoother closing with no bank valuation, no lien, and no risk of a finance rejection killing the sale. That gives you leverage (CarSwitch listings data, July 2026).
On used cars listed between AED 60,000 and AED 100,000, we’ve seen buyers land about 6% below asking. On cars listed between AED 30,000 and AED 60,000, that figure climbs to about 7%. And on cars under AED 30,000, we’ve seen closer to 9% come off.
“Cash buyers close faster, and sellers value that. When there’s no bank in the middle, both sides save time — and that usually translates into a better price.”
Kamel Abbou, Country Manager, UAE, at CarSwitch
A stronger negotiation position isn’t the only thing cash saves you. There’s no interest, no processing fee, and no mandatory comprehensive insurance tied to a lender for years.
Side-by-side: used car loan vs cash on an AED 80,000 car
Let’s put real numbers together. Say you’re looking at an SUV listed at AED 80,000 — that sits right in the AED 60,000–100,000 range where we’ve seen about 6% negotiated off.
| Cost item | Cash buyer | Financed buyer (4% flat, 5 yr) |
|---|---|---|
| Asking price | AED 80,000 | AED 80,000 |
| Negotiated discount | ~6% (AED 4,960) | ~3% (AED 2,400) |
| Purchase price | AED 75,040 | AED 77,600 |
| Down payment (20%) | — | AED 15,520 |
| Total interest paid | AED 0 | AED 12,416 |
| Bank processing fee | AED 0 | AED 750 |
| Total out-of-pocket | AED 75,040 | AED 90,766 |
The cash buyer in this example pays about AED 15,700 less overall. That gap is real — it’s roughly the price of two years’ comprehensive insurance on that car.
Notice the financed buyer’s discount is smaller. That’s because sellers know bank-backed offers come with conditions, delays, and sometimes fall through. Cash simply gives you a stronger hand.
When a used car loan still makes sense
Cash isn’t the right move for everyone. If paying AED 75,000 up front would leave your savings dangerously thin, financing protects you against the unexpected — a job change, a medical bill, a major car repair.
It also makes sense if you can put that cash into something earning more than the loan’s effective rate. At today’s UAE deposit rates (around 4–5% on a one-year term deposit), the maths is close to break-even, especially once you account for the weaker negotiation position. But if you have investments returning well above that, keeping liquidity could be the smarter play.
A few things help if you do finance:
- Put down at least 20% — it lowers your monthly payment and total interest.
- Choose the shortest term you can afford. Three years instead of five cuts total interest by about 40%.
- Check if your bank offers a reducing-rate option — some do, and it’s meaningfully cheaper.
- Look into cars already set up for installments on CarSwitch for a smoother process.
The real question: how old and how much?
Your decision also depends on what you’re buying. A 2018 BMW 3 Series lists around AED 40,000 on CarSwitch — about 80% less than its original sticker. At that price, a used car loan feels like overkill for many buyers. You’re financing a car that’s already lost most of its value, and the interest adds back a chunk of the savings.
On the other hand, a 2022 BMW X4 still lists around AED 187,000 — about half what it cost new. Financing a portion of that makes more sense because the car still holds meaningful value and the loan amount justifies the hassle.
Used cars under AED 30,000: buyers have negotiated about 9% off asking
Used cars AED 60,000–100,000: buyers have negotiated about 6% off asking
A 2018 BMW 5 Series lists around AED 80,000 — about 75% below its original new price of AED 322,500
How to decide
Ask yourself two questions. First: would paying cash leave me with less than three months of expenses in reserve? If yes, finance. Second: is the car priced high enough that the interest makes a material difference? On a car listed at AED 30,000, five years of interest at 4% flat adds about AED 4,800. On a car at AED 150,000, it adds about AED 24,000. The stakes scale up.
Either way, start with transparent pricing. Every car on CarSwitch is inspection-verified with a detailed report, so you’re negotiating from a number that reflects the car’s actual condition — not a guess.
Ready to find your next car? Browse inspection-verified used cars in Dubai and see the real price before you decide how to pay.
Cash usually saves more overall. You avoid interest entirely, skip bank processing fees, and we’ve seen cash buyers negotiate harder — around 6–9% off asking depending on the price range. But if paying cash would empty your savings, a loan with a solid down payment is still a reasonable choice.
Most UAE banks charge around 3–5% flat rate per year. On a five-year loan for AED 64,000, that’s roughly AED 12,000–16,000 in total interest. Flat rate means interest is calculated on the original amount for the full term, so the effective cost is higher than it first sounds.
It depends on the price range. On cars listed between AED 30,000 and AED 60,000, we’ve seen about 7% come off. Under AED 30,000, that figure climbs closer to 9%. Cash gives you more leverage because the seller gets a faster, simpler closing.
Most UAE banks require at least 20% down on a used car. Putting more down reduces your monthly payment and total interest. Some banks may ask for more if the car is older than five years.
