

If you took out a used car loan in the UAE during the past two years, the rate you locked in is probably higher than what banks are offering right now — or it’s about to climb further. The UAE Central Bank base rate just rose to 3.9%, and whether that helps or hurts you depends entirely on when you signed. Here’s how to figure out if refinancing makes sense, and how to do it without overpaying in fees.
The short version
- If your current rate is above 4.5% and you have at least 18 months left, refinancing can save real money.
- Ask your bank for the early settlement figure first — that’s your starting point.
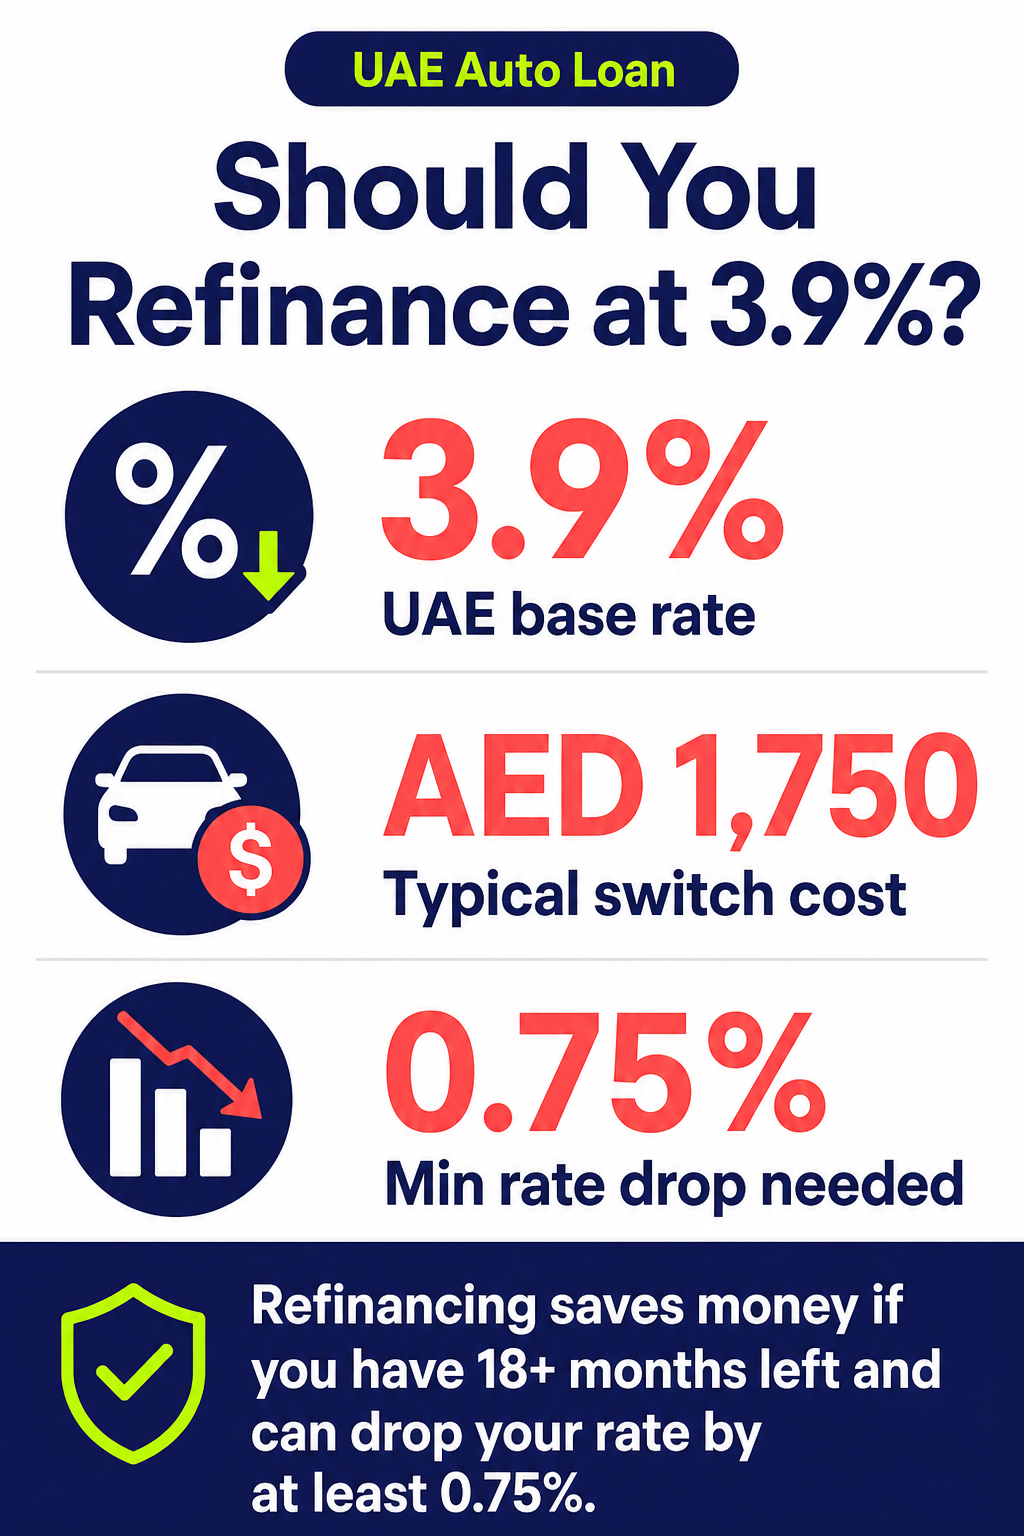
- A new bank’s rate needs to be at least 0.75% lower to cover the switching costs.
- Fixed-rate loans protect you from future hikes; variable-rate loans got more expensive this month.
- The whole process takes about two to three weeks in Dubai.
What actually changed with the rate hike
The UAE Central Bank follows the US Federal Reserve because the dirham is pegged to the dollar. When the Fed raised rates, the CBUAE moved its base rate to 3.9%. That’s the rate banks use as a floor when they price your auto loan.
If you’re on a variable-rate used car loan, your monthly payment likely went up already. If you’re on a fixed rate, nothing changes until your loan term ends. And if you’re shopping for a new loan today, you’re looking at a higher starting point than someone who borrowed six months ago.
Should you refinance your used car loan?
Refinancing only works if the savings outweigh the costs. Here are the costs you need to know about:
- Early settlement fee: Most UAE banks charge 1% of the remaining balance, capped at AED 10,000.
- New loan processing fee: Typically around AED 500 to AED 1,000.
- Mortgage registration / car re-pledge: Around AED 200 at the RTA.
Add those up. That’s your break-even number. If the interest you save over the remaining term doesn’t beat that total, refinancing costs you money.
A quick way to check
Say you owe AED 80,000 with 24 months left at 5.5%. A new bank offers 4.25%. Your settlement fee is AED 800, processing is AED 750, and the RTA charge is AED 200 — so about AED 1,750 to switch. The rate drop saves you roughly AED 1,000 per year in interest, so over two years that’s about AED 2,000. You come out ahead by around AED 250. Not life-changing, but it’s real.
If you only have 12 months left? The maths usually doesn’t work. You won’t recover the fees in time.
| Balance remaining | Months left | Old rate | New rate | Approx. switching cost | Approx. saving | Worth it? |
|---|---|---|---|---|---|---|
| AED 80,000 | 24 | 5% | 4% | AED 1,750 | AED 2,000 | Marginal |
| AED 80,000 | 36 | 5% | 4% | AED 1,750 | AED 3,000 | Yes |
| AED 120,000 | 36 | 6% | 4% | AED 2,150 | AED 6,000 | Yes |
| AED 60,000 | 12 | 5% | 4% | AED 1,550 | AED 600 | No |
How to refinance step by step
- Get your early settlement letter. Call your current bank and ask for the exact payoff amount. They’re required to give it to you.
- Shop around. Compare at least three banks. In the UAE, Emirates NBD, ADCB, FAB, and Mashreq all offer auto refinancing. Ask for the flat rate and the reducing rate — the reducing rate is what you actually pay.
- Apply with the new bank. They’ll need your Emirates ID, salary certificate, bank statements (three to six months), and the settlement letter.
- New bank pays off the old loan. This happens directly between the banks. You don’t carry cash.
- Re-pledge your car. Visit an RTA service centre in Dubai to transfer the vehicle pledge to the new lender. Takes about an hour.
Start to finish, the process usually takes two to three weeks in Dubai.
What if you’re buying — not refinancing?
If you’re looking at a used car loan right now, the 3.9% base rate means your offered rate will sit somewhere between 4% and 6%, depending on your salary, employer, and the car’s age. Banks in the UAE typically won’t finance cars older than five years, and the loan-to-value ratio is usually capped at 80% for used vehicles.
Here’s something worth knowing: according to CarSwitch listings data from July 2026, cars that still carry manufacturer warranty hold about 5% more value than those without. That matters to the bank, too — a car with warranty is easier to approve and may qualify for a slightly better rate.
Cars with manufacturer warranty command about 5% higher prices than equivalent cars without (CarSwitch listings data, July 2026). A minor accident history knocks about 9% off a car’s value. SUVs make up 63% of all CarSwitch listings.
That warranty figure isn’t just about resale. When a bank appraises your next car for financing, a model still under warranty looks like a safer bet. It can shave a fraction off your rate or get a faster approval.
“A lot of buyers don’t realise the warranty status of the car directly affects their loan terms. It’s one of the first things banks look at during appraisal.”
Ramiz Islam, Head of Marketing at CarSwitch
If you’re browsing used cars in Dubai, every listing on CarSwitch is inspection-verified with a 200-point check — so you’ll know exactly what condition the car is in before you take it to the bank. You can also explore car installment options directly on the platform.
Fixed vs variable: which protects you now?
With rates at 3.9% and the possibility of more hikes, a fixed-rate loan locks in your payment. You pay a small premium for that certainty — usually about 0.25% to 0.5% more than the variable option at signing.
A variable rate is cheaper today but carries the risk that your monthly payment climbs with every future hike. If you’re financing over three years or more, fixed is the safer call right now.
What to do next
If you already have a used car loan, call your bank this week and ask for the early settlement figure. Compare it against two or three offers. If the savings beat the fees, move. If they don’t, wait — rates may shift again.
If you’re shopping for your next car, start with a car you can trust. Browse inspection-verified cars in Dubai on CarSwitch — every one comes with a detailed report so you know what you’re financing. And if you’re looking to sell your car to fund the switch, real people are here to help you through it smoothly.
It depends on your current rate, remaining balance, and how many months are left. If your rate is at least 0.75% higher than what a new bank offers and you have 18 months or more remaining, refinancing can save you money after fees. If you have less than a year left, the switching costs usually eat up the savings.
The main costs are an early settlement fee (usually 1% of the remaining balance, capped at AED 10,000), a processing fee at the new bank (around AED 500 to AED 1,000), and an RTA re-pledge fee of about AED 200. Add them up and compare against your interest savings.
The whole process typically takes two to three weeks. The longest part is the new bank’s approval. The RTA visit to transfer the vehicle pledge takes about an hour.
With the base rate at 3.9% and the possibility of further hikes, a fixed rate gives you certainty. You’ll pay slightly more upfront — usually about 0.25% to 0.5% — but your monthly payment won’t change if rates rise again.
